
The Briefcase #61: Taxing Temptation
Written by: AccountingCPD | Published: 2nd Oct 2026 | Updated: 2nd Oct 2026
A fancy chocolate bar hiding in your cupboard might seem like a private indulgence, but these extravagances are more often than not a matter of public tax law. UK readers may remember the famous VAT tribunal over whether a Jaffa Cake is a biscuit or a cake. It is a cake, by the way, because it goes hard when stale, instead of soft.
That particular dispute wasn’t centred around whether Jaffa Cakes are good for you. Other taxes, however, are explicitly intended to curb our hedonistic desires through punishing pricepoints. In this week’s Briefcase, we’re looking at the history of taxing temptation, and some of the more unexpected things that have attracted a charge around the world.
Cigarettes and alcohol
In 1604, James I published his Counterblast to Tobacco, setting out his objections to smoking. These included concerns about its effects on health, alongside social and moral complaints. That same year, he sharply increased tobacco duties in an attempt to discourage its use. The Library of Virginia records both the tax increase and its connection to his opposition to tobacco.
Incidentally, “counterblast” is a satisfying synonym for “objection”, and one worth borrowing the next time you’re trying to fill the subject line for an email reiterating that the herbal teabags in the office cupboard are not communal, they are yours. A Counterblast to Communal Tea.
The 1736 Gin Act supplies another early example of tax being used to punish social ills. The Act imposed a £50 licence fee on gin sellers as part of an attempt to curb the trade, and concerns about drunkenness and social behaviour were central to the debate. Have you ever seen those old Hogarth illustrations? Women sprawled out on a Whitechapel street while their sons play cards on a tombstone? The streets were awash with gin!
But, we maybe shouldn’t take the government line so readily. Instead, we should ask the big question: was the intention to change consumption, or profit of the evil that men do?
When the accountant asks for the recipe
Denmark introduced a tax on chocolate and confectionery in 1922. The tax has proved remarkably durable, too. Denmark planned to abolish its chocolate and confectionery tax, along with its coffee tax, from July 2026, but the proposal was rejected by parliament just days before it was due to take effect. More than a century on, chocolate is still considered bad for you.
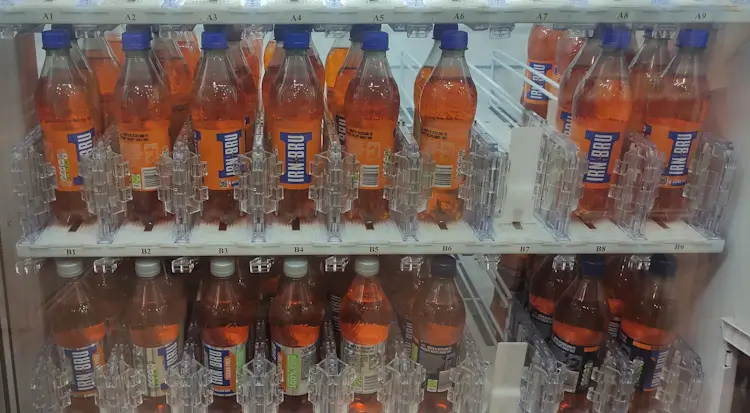
For a more explicitly health-focused example, there’s the UK’s Soft Drinks Industry Levy, which took effect in 2018 after years of campaigning around sugar consumption, including from TV chef Jamie Oliver. It applied to producers and importers of qualifying drinks containing added sugar, with bands based on sugar content. Encouraging manufacturers to reformulate their drinks was part of its stated purpose.
That created an interesting alternative to simply charging more for the same product. A manufacturer could change the recipe, potentially moving the drink into a lower band or outside the levy. The financial calculation could begin before anybody reached for a bottle in the supermarket.
The result was that they ruined Irn-Bru, but we’ll keep drinking that garbage.
Please declare your snacks
Mexico decided to go further than any other country when, in 2014, it introduced an 8% tax on specified categories of non-essential, energy-dense foods containing at least 275 kilocalories per 100 grams. This covered products like confectionery, certain cereal-based foods and frozen desserts.
A product could be energy-dense without automatically falling within the tax, which means that, somewhere along the line, somebody had to start reading nutritional labels with the seriousness normally reserved for a set of management accounts. The sort of thing you do on the toilet when you forget your phone, but as a job.
There are probably worse things to spend an afternoon scrutinising than a biscuit specification. When you’re going through financial reports, you can’t daydream about what they taste like.
When the tax gets very specific
Tonga has used higher taxes on foods – including turkey tails and mutton flaps – alongside sugary drinks, as part of attempts to tackle diet-related disease.
If you’re wondering what a mutton flap is, you’re probably not alone. It’s the breast or lower-rib section of a sheep; a cheap, fatty cut that has been widely consumed in parts of the South Pacific. Turkey tails occupy a similar niche. They’re exactly what they sound like, and they’re also notably high in fat.
It’s a useful reminder that “health tax” can mean something very different depending on where you are. A culture that gorges itself on Irn-Bru is more likely to face a tax on soft drinks than one that can’t resist a turkey tail.
Even your tan has a tax treatment
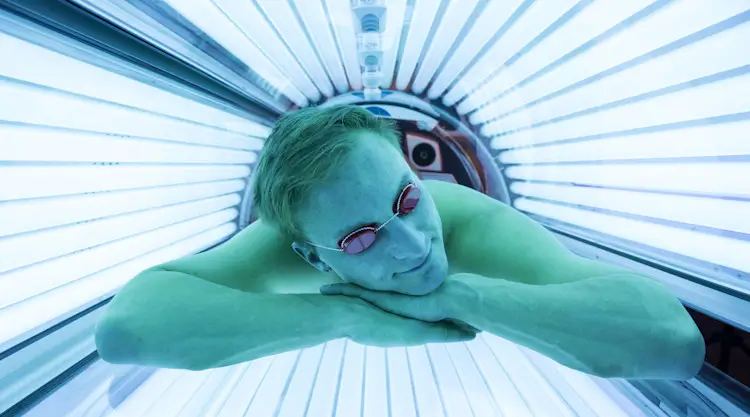
Food, drink and tobacco aren’t the whole story. In July 2010, the United States introduced a 10% federal excise tax on indoor tanning services. The definition concerns services using ultraviolet lamps to induce tanning. It excludes medical phototherapy performed by a licensed medical professional, while IRS guidance also makes clear that spray tans and topical tanning creams and lotions are outside this particular tax.
The paperwork gets more familiar when services are sold together. IRS guidance explains how to allocate a bundled price where tanning is included alongside other services, even when the tanning is described as “free”. Part of the payment may still be attributable to it.
Most colleagues, on seeing someone return to the office with a glow, might ask whether they had a nice holiday. An accountant who has spent too long reading the guidance could end up asking the freshly tanned colleague whether it was ultraviolet or a topical application, before launching into “I ask because…” and delighting their conversation partner with their worldliness.
🧠 Final thoughts
The history of taxing temptation is a muddled one. There are a lot of different motivations at play, and it can be hard to untangle “is this for the good of the public?” with “is this a way of scraping a few quid from the good people at the Coca-Cola corporation?”
What makes them particularly interesting for accountants is the detail. “A sugary drink” eventually becomes a question about grams per 100 millilitres. “A tan” becomes a question about the machinery involved. Everyday purchases turn out to have rather more going on behind them than the receipt suggests.
Back at your desk, you might find yourself reading the back of your sweets bag with renewed professional interest. There could be a perfectly legitimate tax question in there, just waiting to be unwrapped.
Ready to power up your CPD?

Updated 2nd Oct 2026 | 6 min read